If you’re buying a home in Central Florida, Florida home insurance should be part of the conversation before you completely fall in love with the house. I say that as a Realtor, but also as a lifelong Central Floridian with four generations of roots here and decades of firsthand experience living through Florida weather in very different homes and communities.
I’ve watched trees come down around me during the 1993 “Storm of the Century”, prepared for three major hurricanes in a matter of weeks while caring for young children and pets, flooded in newer construction that sat in Flood Zone X, ridden out hurricanes directly on the Atlantic Ocean, and experienced Ian and Nicole in Ponce Inlet.
Florida Weather Has Taught Me A Lot
The biggest lesson may be this: Never assume you understand a home’s risk simply because of its age, ZIP code, flood-zone designation, or how beautiful it looks in the listing photos.
My Florida Storm Education Started Early
I was newly out on my own when the 1993 “Storm of the Century” hit the Zellwood/North Apopka area where I was living. I remember the house shaking violently that night. Trees and homes came down around me. When daylight came, the destruction in the surrounding areas was difficult to process. One nearby home had been torn apart so completely that very little remained, yet somehow a single recliner was still sitting there, facing outwardly as if someone had simply been watching television throughout the storm-completely untouched.
I have never forgotten that sight. Luckily, my home escaped damage, but that storm taught me very early on that Florida weather deserves respect.
2004 Taught Me That Choosing the Home Matters Before the Storm Arrives
Then came the 2004 hurricane season.
Hurricanes Charley, Frances and Jeanne rolled through Florida within weeks of one another. At the time, I was living in Lake Mary with my young children and pets, so hurricane preparation wasn’t casual. I was thinking about keeping everyone safe, having water, maintaining power, preserving food, figuring out how we’d have hot meals for the coming weeks without water or power. And mostly- I was thinking about what we would do if normal life suddenly stopped.
Why the Property Itself Mattered
We were living in a newer condo building with a newer roof and newer utility infrastructure directly in front of a retention pond and newly finished community pool area. Because of this new community addition, our building was linked to the newly installed power grid for the 2nd pool. We prepared for the worst, but the home performed remarkably well: we never lost power, water or cable, and we didn’t flood. Yet, every other building there- and many surrounding neighborhoods did lose power. Many were without water for days as well. And of course cable and internet were down for them even longer. Central Florida took a hard hit that year from those storms but once again- I felt extremely fortunate that I had prepared, and we were ultimately spared.
That experience doesn’t mean newer construction is automatically safe. It isn’t.
But it reinforced something I still believe today: Sometimes the smartest hurricane preparation starts long before the storm appears on the radar-when you choose which property to buy. Roof condition matters. Construction matters. Drainage matters. Elevation matters. Utilities matter. And the infrastructure surrounding the property can matter too.
Tropical Storm Fay Flooded My Zone X Home
In 2008, I learned a very different lesson. I was living in a beautiful 2 story new construction home in Sanford. The neighborhood was new. The property was in Flood Zone X. From all accounts- we sat ‘high & dry’. Nothing about it suggested to me that I was about to become a flood story. And the timing could not have been worse.
Tropical Storm Fay arrived during what was supposed to be my daughter’s first birthday celebration. We had planned the party, spent the money, had people flying in from all over the United States and were excited to celebrate her special day. Instead, the storm forced us to cancel everything. Then the rain kept coming. And coming. And coming. And then my house flooded.
I had always noticed the grading seemed a little “off” on the lot our brand-new, two-story house sat. It was one of the last homes built on that neighborhood, and it was close to the retention pond. The backyard sat higher than the area surrounding the house, but up until this point it hadn’t really caused much of an issue. Just a few puddles would form out back during our normal afternoon thunderstorms. Although I knew the pitch of the yard didn’t feel right, and we had the puddling-we still didn’t pay it much mind- unfortunately.
Why It Mattered
Lesson learned. During Fay, that mattered. It was a slow moving tropical storm that hung over Florida for a few days. Floridians are used to tropical storms, but Fay wasn’t the usual TS we were used to. And Fay over-welcomed her stay. She moved at a snail’s pace. Literally. The rain was constant- non-stop- for days on end. Heavy rains. The waters in Lake Monroe rose- and kept rising.
For myself, I lived in a brand new construction home and I was comfortably sitting on the couch with my one-year old watching the news explaining why her birthday celebration was on hold. As we sat there together, I began to notice a line forming across my wall behind the TV. As I sprang toward the windows to look outside-> that’s when I saw the water standing nearly to the bottom of them and quickly seeping into the walls. Before we knew it, we were dashing upstairs as the water began to enter out first floor. That experience permanently changed the way I look at all Florida properties now.
Flood Zone X Does Not Mean You Cannot Flood
I actually have a line that I use when people tell me they aren’t worried about flood insurance because they’re in Flood Zone X: “Does your driver’s license say FL anywhere on it? Then I want you thinking about flood insurance.” I’m being intentionally dramatic when I say it, but i mean it. Not every Florida property is in a high-risk flood zone. However, after Tropical Storm Fay, I no longer confuse lower mapped flood risk with no flood risk.
Flood maps and flood risk information continue to change as communities, FEMA and local agencies update data and mapping.That’s one of the reasons buyers should verify the current flood designation for a property rather than relying on old information or assumptions. Florida sellers have disclosure obligations regarding certain known flood-related information. Buyer’s should review t\he seller’s disclosures carefully and ask questions about any known history of flooding or water intrusion. It doesn’t necessarily mean that the property will flood again anytime soon- but it does mean that extra precautions should be taken if you decide to purchase that property and ride out any future storms. This shouldn’t alarm you, it’s just imperative that you’re properly informed before deciding to purchase any properties.
And this is something every Florida buyer should understand: Standard homeowners insurance generally does not cover flooding caused by rising water. Flood coverage is a separate conversation. So even if your lender doesn’t require flood insurance, I still believe it is worth getting a quote and making an informed decision. You’ll be happy you did, should you ever find yourself in the predicament I was in back in 2008. I learned that distinction the hard way- and I’m hoping you won’t ever need to.
Look at the Yard, Not Just the Flood Map
Because of what happened to me, I look at the land around a house very differently now. Where does the water go? Is the backyard higher than the house? Does the lot slope toward the structure or away from it? Where are the storm drains located? Does the road hold water after an ordinary Central Florida afternoon storm? What are the neighboring lots doing? Can you see evidence of drainage work? Where would water naturally collect? How far are the retention ponds? How many ponds are in the neighborhood? How high do they get in normal storms? Are they always at full capacity?
Those are not glamorous questions. But neither is standing inside your home while water comes in. Trust me. A beautiful kitchen can be remodeled. How an entire property handles water deserves just as much attention.
New Construction Does Not Mean Nothing Can Go Wrong
My Tropical Storm Fay home was new construction. That is exactly why the words new construction do not automatically make me stop asking questions. Newer homes can absolutely offer advantages. But a builder can still construct a new house on a poorly graded lot. A drainage system can still be inadequate. Water can collect somewhere it shouldn’t. A brand-new neighborhood may also experience conditions that homeowners haven’t yet witnessed simply because it hasn’t existed long enough.The year built is useful information. It is not the whole story.
Then I Took Florida Storm Living Directly to the Atlantic Ocean
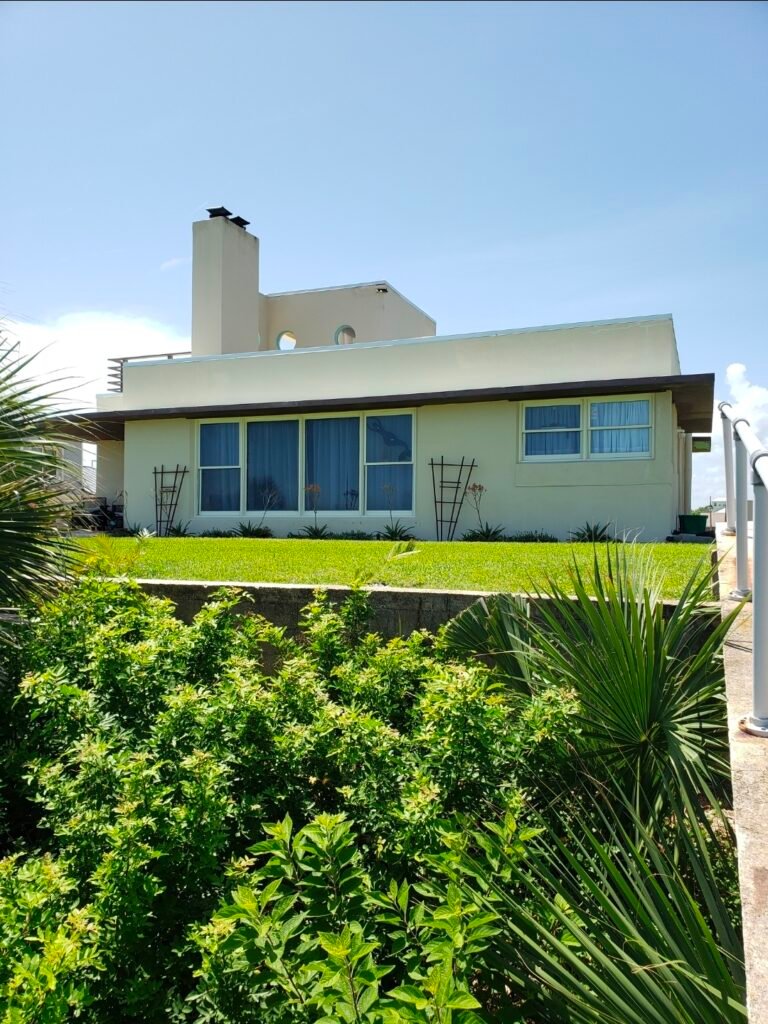
Years later, I lived directly on the Atlantic Ocean in Daytona Beach Shores, right off A1A. And when I say directly, I mean directly. The home was one of the most interesting places I’ve ever lived: an older poured-concrete beach house with a Dr. Phillips family connection, huge original windows facing the ocean and even an old wine cellar and bedroom/bathroom suite built below grade. It had a 3rd story rooftop lounge/sundeck with the most incredible views of the sunrise over the coastline. It was remarkable!
Public records date the property to 1947, although I was told by the owner and longtime neighbors that construction paused partway through and the house was ultimately completed several years later. Either way, it was a fascinating piece of old Florida history. Its architectural design reminded me strongly of “Frank Lloyd Wright”- one of my all-time favorite architects. I absolutely loved living there! It was also not what most people would picture as an ideal hurricane setup. Those enormous original ocean-facing floor to ceiling windows certainly didn’t look too reassuring. Yet I rode out a couple of major storms there, including Hurricane Matthew in 2016 and Hurricane Dorian in 2019.
Riding Out Matthew and Dorian
We prepared, settled in, watched movies, played board games and observed the magnificent force of weather roll in from the Atlantic Ocean through the third-story original porthole windows. It was not scary at all- it was actually quite invigorating. We felt completely safe there. And we were. During one of those storms, I fell asleep on the couch, watching movies on Netfilx- directly in front of those big ominous windows while the weather raged outside. I thought I would stay up all night and keep an eye out, but alas I did not. I slept through it like a baby. And somehow, throughout those storms, we never lost power, water, or cable.
What the Morning After Taught Me
The following morning was surreal. Homes nearby had taken on significant damage. Roofs were gone from properties across the street. Walls had crumbled on many homes nearby. Trees down everywhere. The streets were basically impassable due to flooding and debris for miles both ways. Dark clouds with a mix of peacefulness and sorrow hung heavily overhead. The mere silence was deafening. All you could hear was the ocean waves as they roared in, but everything else was silenced.
It was quite the surprise to walk outside in the morning light to see that the house next door had a huge ice vending machine that had blown over from the local 7-Eleven from about a half mile away- smashed up against the front door. The house eventually caught fire and burned down from the inside out due to an electrical fire that started from a spark from an electric couch. Yet my home and yard were completely untouched. No structural damage. No meaningful debris. Not even my rose garden or fresh vegetable garden that sat directly facing the Atlantic Ocean had been disturbed. How could the homes all around us be devastatingly destroyed, and yet my rose bushes hadn’t lost even a petal?
That’s Florida Weather for You, Firsthand
It honestly felt as if someone had placed a glass bowl of protection over the entire property. I don’t tell that story because I believe that house was magically storm proof. It wasn’t. I tell it because Florida storms have repeatedly shown me that two properties only yards apart can experience the same event very differently. Construction type can matter. Elevation can matter. Exposure can matter. Roof condition can matter. Drainage can matter. Surrounding structures can matter. And sometimes, yes, luck matters too. That house taught me to look beyond when a home was built and start asking how it was built.
In 2022, Ponce Inlet Taught Me to Pay Attention to Infrastructure
By 2022, I had just moved off the direct coastline and had chosen a 2 story townhouse in Ponce Inlet overlooking the Halifax river when Hurricanes Ian and Nicole hit the area back-to-back. Many homes around me flooded. Huge mansions across the street were literally falling into the ocean in real time. It was all over the national news. It was kind of a big deal. Several of my neighbors were without power for about a week. Many of the hotels and Condos up and down A1A were hit pretty hard. Even some of the beach accesses were left completely unusable.
Our Eastern Coastline Had Forever Been Changed
Even my previously safe A1A home had received damages. The solid concrete walkway to the beach, along with the seawall were damaged. The same walkway that had stood so far above sea level for so long, was completely destroyed and laying on the sand with the ocean water rushing all around it. It was surreal. Over 75 years strong-> washed away overnight.
It was a madhouse because not only was Ponce Inlet flooded out- so was everywhere else that normally did not flood. There was nowhere to go that you couldn’t see or feel the devastation first hand.
My home? Once again-my home never lost power., water, or cable and wifi. No debris in my yard. Zero damages to our vehicles. A newer roof gave me confidence in the structure, but another factor also stood out: my understanding was that my property shared a power circuit with the nearby police station. That reinforced another lesson I now talk about with buyers:
Why I Pay Attention to Utility Infrastructure
Pay attention to the infrastructure around the house. That does not mean buying near a police station, fire station, school or hospital guarantees you will keep power. Utility grids are complicated, and proximity alone does not prove that a house shares a particular circuit. But I absolutely pay attention to what is around a property. I pay attention to whether utilities are underground or overhead, where transformers and power lines are located. and whether the neighborhood seems to lose electricity during ordinary afternoon storms. Most buyers are looking at the kitchen. Sometimes I’m looking at the power poles too.
Preparation Changed the Way I Experience Florida Storms
When I was newly out on my own during the 1993 storm, I remember fear. A lot of it. In 2004, I had young children and pets depending on me, so preparation became serious. Tropical Storm Fay in 2008, taught me not to trust a flood-zone designation blindly- and that slow moving tropical storms can do even more damage than most people expect due to the high water volume it brings with it. Living directly on the Atlantic taught me how differently neighboring structures can perform. Ian and Nicole reinforced the importance of infrastructure.
Today, when a major storm approaches, I don’t spend the entire time frightened. I prepare myself, the property, and the supplies we may need. Water, electricity, communication, insurance and evacuation plans all get thought through ahead of time. Once I’ve done what I can responsibly do, I can respect the incredible power of the storm without allowing fear to take over. Preparation changes everything.
Of course, if emergency officials issue evacuation or shelter instructions, follow them. No house or possession is worth gambling your safety. Ever.
Start Your Florida Home Insurance Research Early
All of this brings me back to Florida home insurance and why it’s so important to start your due diligence early. I don’t want buyers waiting until the final few days before closing to discover that the home they have already emotionally purchased is difficult or unusually expensive to insure.
Roof age and condition can have a major effect on Florida home insurance availability and cost. Start asking questions from the beginning. Two houses with the same purchase price can create very different ownership costs. Sometimes the cheaper house isn’t actually the cheaper choice. That is why I want buyers researching Florida home insurance before the final days of a transaction.
What Is a 4-Point Inspection?
A 4-point inspection looks at four major systems: Roof. Electrical. Plumbing. HVAC. Insurance companies may request one when underwriting an older Florida home, depending on the insurer and the property. This is another reason I encourage buyers to look beyond cosmetic renovations.
A beautiful kitchen doesn’t tell you how much life remains in the roof. Luxury flooring doesn’t tell you what electrical panel is installed. Fresh paint doesn’t tell you what is happening with the plumbing. Those systems may matter considerably more to an insurance company than the things designed to make you fall in love during a showing.
I have always, and will always highly recommend a full inspection- regardless of how you plan on purchasing the property. Even with a cash sale where it’s not required-get the inspection!
Why Wind-Mitigation Inspections Matter
A wind-mitigation inspection is different from a 4-point inspection. It documents features intended to help a home perform better in high winds. That may include roof attachment, roof-to-wall connections, roof geometry and opening protection. Qualifying features may also affect insurance pricing. I would never promise a buyer a specific savings amount because every property and insurer is different. But I absolutely want to know whether a wind-mitigation report exists.
Do Not Compare Florida Home Insurance Quotes by Premium Alone
If one quote is cheaper than another, don’t stop at the annual premium. Ask what you are actually buying. What are the deductibles? Is there a separate hurricane deductible? What is excluded? How is the roof handled? What about water damage? What mitigation credits were applied? Is flood coverage separate? The cheapest premium is not automatically the best protection. When comparing Florida homeowners insurance options, the annual premium is only part of the picture.
Florida Home Insurance Is Part of the Home-Buying Decision
Insurance should not be paperwork you deal with after deciding the house is “the one.”
It belongs in the decision itself. If two homes are otherwise comparable but one has a newer roof, better drainage, documented wind-mitigation features and easier insurance options, that belongs in the comparison. So does utility infrastructure. So does grading. So does flood risk.So does construction. And sometimes, so does the road outside the house. Buying a home in Florida means buying the entire property and the environment it lives in—not just the square footage inside the walls.
What I Want Central Florida Buyers to Remember
I want buyers to remember I’m a Realtor and Florida resident myself, not an insurance agent. Flood coverage and Florida home insurance are related conversations, but they are not the same coverage. Coverage, premiums, deductibles and underwriting requirements should always be discussed and confirmed with a licensed Florida insurance professional.
What I can bring to the conversation is something different: decades of actually living here, buying properties, surviving the storms, and the first-hand knowledge those experiences have taught me. Over the years I’ve watched trees come down, seen homes destroyed, neighborhoods flood, and families lose utilities for days/weeks. I’ve also experienced hoes that have done remarkably well through major storms. Those experiences changed the way I evaluate Florida property.
First Hand Experience Makes A Difference
Those experiences changed how I evaluate Florida property. I don’t believe buyers should be afraid of living here. Not at all. Clearly, I’m still here. I love Florida. But I believe informed buyers make better homeowners. Understand the house. Understand the land. Understand the insurance. Understand the infrastructure. Have the proper inspections. Prepare wisely. Then enjoy everything that makes Central Florida such an extraordinary place to call home. No matter where you choose to live, mother nature will be there. My best advice is simple- respect it, and prepare for it.
At Burkhart & Foster Collective, that’s part of what we mean when we talk about looking beyond the listing photos and understanding the property you’re actually buying. We understand how important it is to feel safe in our homes, and we are happy to help guide you in understanding the preparations to do so too.
Experience the Difference From City to Coast
Burkhart & Foster Collective
Brokered by LPT Realty LLC
Have questions about evaluating a property or planning your Central Florida home purchase?
Contact Burkhart & Foster Collective at (407) 519-0007 to discuss your goals with our team. Let our Expertise help guide you in choosing your next Central Florida home. burkhartfoster.com